Showing posts with label Fraser and Neave. Show all posts

Wednesday, November 21, 2012

Letting go of iCap

I have decided to let go iCap. As mentioned before, while I think that iCap has a good manager, the investment ideas may not suit me. Anyway, I am selling to be able to buy some other stocks in future. The reason I bought iCap was due to it was really cheap. Now it is still cheap but not as cheap when I bought it at RM2.17. I have sold it at RM2.36 despite iCap hovering around RM2.4+ last week. Have to admit I am not a good seller.

Actual amount made over 4 months
Whatever it is, I think that the fight for board positions may not be over with today's large volume traded. Although, City of London Investment Fund has sold some stocks over the last few days, Laxey Partners may buy more. However, it remains my speculation for now.

ICap is now trading at a discount of 19.5% from its last week's NAV. Its major holdings remain to be PetDag, Padini, Parkson, F&N and Boustead.

Among the holdings, these are how I see it.

Petronas Dagangan

I like PetDag despite we seeing more and more oil and gas companies moving into the upstream side of the market. We saw BP letting go of the retail business many years ago and if I am not mistaken I am seeing many of Exxon-Mobil's branded stations changed to a brand called Petron. The letting go of the retail side of business could be good for PetDag in the longer run.

Padini

I have mentioned of my liking for Padini before, hence not repeating.

Parkson

As I like AEON and Tesco, I do like Parkson as well but the Malaysian operations only. Parkson is however heavily dependent on its China's income. For its China's operations, I am not able to reckon the position it is in. My guess is that the competition is getting really stiffer with Wal-Mart, Carrefour, Tesco fighting really hard in the hypermart business. Parkson's positioning is different but it is bound to affect Parkson no matter what. The 3 players are the largest retailers in the world ranking 1, 2 and 3. Where is Parkson? That could have affected the Malaysian owned retailer.

As for Parkson's venture in Indonesia and Vietnam, it is too early to tell the impact it is going to have onto the retailer.

F&N

Good company but its competitors are better brands and much bigger. I see its price as expensive although it does try hard diversifying into properties the next few years to cushion the negative impact.

Boustead

Great assets but I always have doubts on armed forces running companies. If you happened to be in Damansara, just compare One Utama (private owner, See Hoy Chan) against The Curve (Boustead). They are not far from each other. Which one you think has more potential or already is on the home run? This reflects management capabilities, in the eyes of an investor.

I always have the feeling that since most plantation, banks, properties stocks were doing well, Boustead will of course do well. Warren Buffett used to say, "Only when the tides are down, we will know who has been swimming naked."

Out of the largest 5 holdings, I like 2-1/2, hence may not suit my taste for now.

Monday, November 12, 2012

Run Fraser Run!

F&N is more than 100 years old. Usually for a company this age, it's nice to be able to have an occasional walk, sometimes jog while still continue to maintain that level of comfort as well as fitness. For a while, F&N has been enjoying such. As I have mentioned in earlier article, watch out for its deterioration as well as the increase in competition.

Its results for the last financial year has shown signs that it is gearing itself to be fit enough to run. It has moved its dairy operations to Pulau Indah. The Seksyen 13 land is to be turned into a mixed development project. Hence, I can say that it has tried very hard to be what it is over the last many years.

That poor 4th quarter results is being cushioned with announcement of its planned RM1.65 billion project. As it seems to be so, I think the job for F&N for now is trying to reduce the negative results that are to be seen in its food and beverage business in years to come.

At the moment, the concentration for F&N is to increase market share using brands like 100Plus, Seasons, new cola drink - MyCola etc to fend off competition. While I am allright with companies like Top Glove, NTPM in using reducing margin or aggressive pricing strategy to kill off competition, the competitors that F&N is trying to beat - Coca-cola and Pepsi - will never be killed. The more you try, the harder they will come to hit you. That's the biggest problem facing F&N because these 2 larger players are global giants while F&N is fighting it as a local champion.

Seeing F&N is like sending our best Malaysian (or Singaporean) Muay Thai exponent to Thailand to compete where Thailand will forever produces many quality exponents while once a while Malaysia will try to produce our local best whom can be exceptional.

As can be seen below, despite garnering better revenue (except due to the impact from Thailand's flood) from its existing lines of business, the margin will continue to be thinning. This is because a 500 pound gorilla in Coke is also using a similar strategy to build market share.

To top it off, its dairy business is not performing as well either except for some one-off recognition as below. As opposed to companies like Dutch Lady and Nestle, its lines of products from the dairy business like the evaporated and condensed milk is not as wanting. F&N does have Magnolia but the brand again is a tougher one to pull off as compared to the "Nestle and Dutch Lady".


Frankly, although F&N will continue to be profitable, I think next few years ahead will be challenging for F&N as it is trying to introduce new lines of successful products while some other F&N competitors with less new challenges will have it easier.

As the saying goes in investments, "Never try to attempt to scale the height of a five foot pole. Look out for those that you can just walk over." At the moment, some of the challenges that F&N has are 3 to 5 feet high.

Thursday, August 2, 2012

Any bidder (especially Coke) is good for F&N Malaysia

My previous article on F&N is getting it tougher with Coca-cola going alone may not create friends, as there are quite many who loves the stock. I do as well since now I hold ICap who has F&N as stakes in the closed-end fund.

The latest to join in the fray to acquiring some bits of F&N is Coke itself - once a friend, now an enemy. The piece by Bloomberg is quite comprehensive as well as tells that Coke is only interested in F&N's soft drinks business - which I think could be very true. Now with the multiple parties interested in different bits and pieces of the business, it tells that there is a huge potential, F&N may be split. Its brewery business is seemingly important for Heineken, Thai Beverage. Kirin is reportedly interested in the soft drinks and dairies businesses - to me a surprise.

How do I see it? Coke is interested in the soft drinks business, which is similar to thoughts from Bloomberg's reported piece. 100 Plus is valuable. Others not so much but it will help Coke to eliminate competition such as the F&N's branded fizzy drinks. I however feel that Coke will be buying it at a fair price or maybe a slight premium. Remember, Warren Buffett used to chair the company (he does not control) and he had used before his power or influence to reject Coke's purchase of Gatorade because of price (at that time, controlled 90% of the sports drinks business in US). Of course now, Gatorade is owned by Pepsi.

That DNA I feel is planted into Coke until today, and I do not think that Coke will purchase at a overly high price. One of the reason they are interested is because since parties are interested in mainly the brewery business, the soft drinks piece is up for grab at a much attractive price. Buyer like Heineken may opt for partners as they may be interested in the beer business alone.

In any case, if F&N is up for sale (and seemingly it is), it might as well sell all the food and drinks business as keeping any single one (i.e. either beer, dairies or soft drinks) is not helping its cause. The only one they probably can hold onto is the property arm (where Singapore is bigger - for now).

Now I am wondering who is interested in the dairy business besides just pure investors?

I am wondering why is it that F&N Singapore is suspended while F&N Malaysia is not as at today.

Monday, May 7, 2012

F&N 1H2012 Results: Worse than expected

Usually first quarter of any year is supposed to be the best quarter for F&N, due to Chinese New Year. Not this time around though. Just look at what they have reported.


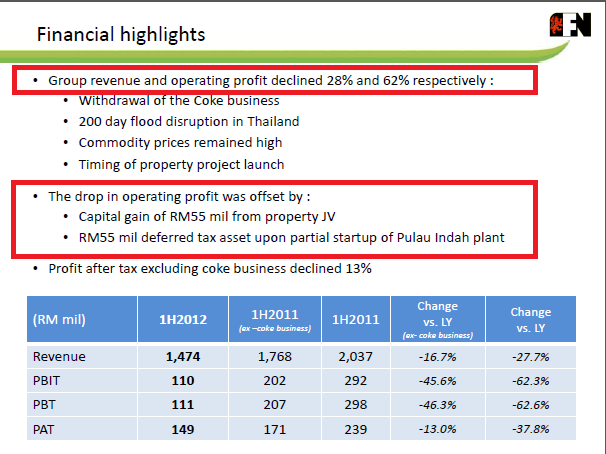
Its poor performance has only been cushioned by the 2 factors - capital gain and deferred tax asset from the Islamic food hub in Pulau Indah which totaled to RM110 million (as reported). These 2 items are not recurring item, hence the significance is not going to be that important.

As I would have expected (in fact I underestimated the impact), the two horse race in the soft drink industry has now become a three horse race - and F&N is the underdog. From there together with the impact from the flood in Thailand, revenue dropped 28%. With 28% drop, the operating profit dropped even more by 62%. So what you see is that any drop or increase in profit from this business is not proportioned to the revenue. The higher the revenue, the profit will increase even more in percentage terms, vice versa.

Now F&N is not enjoying that though. The extremely good results for F&N over last few years was probably due to when Coke was building its own distribution (since the announcement of the split), F&N was probably squeezing the last drop it could have gotten from Coke in that 2 years. Hence, what we saw was the good two years of F&N in 2009 until 2011.
So September 2011 was when the party ended.

And guess what, any company that has lost a good business would obviously be looking for other opportunities - desperately quick. F&N as a result is looking at the dairy business to expand on. By going bigger into that area of business, it is obviously attacking into other competitors that are protecting their turf. From there, you would noticed that the dairy business now will have price competition as well - to the consumers advantage - hence lower margin for the players.

In fact F&N is attacking on all fronts - properties included (through Seksyen 13 land where the old plant is situated). Do you however have that feeling that property is a little bit overpriced at the moment? And if you are interested in a property company, buy a pure property player! F&N is more of a food company.

For this space, Nestle is a better bet despite being expensive as well.

Sunday, March 18, 2012

F&N: Why Coke is derailing its growth

F&N Malaysia has for many years provided happiness to its shareholders. It is a much professionally well run company, executed the property plan perfectly, continue to build its brand value well and along the way gave good dividends to its shareholders as well as capital appreciation  - all the things you couldn't have asked for better for a shareholder. The results as below:


Note that there are 2 F&Ns. 1 is listed in Singapore, the other in Malaysia. The one I am talking about is F&N Malaysia which has its operations mainly in Malaysia and dairy products in Thailand. F&N Singapore, the holding is much bigger and both are just as well run.

All the good things will not come to an end but one very significant factor will derail F&N's competitive advantage for quite a while. What is that?

The Coca-cola company factor

Once a good partner, now a major nemesis in Malaysia. Why is that? F&N used to be the bottler for Coke - for more than 50 years remained that way. When Coca-cola was just happy with building its Cola range and maybe Sprite's market share in every country that it goes to, F&N of course was just as happy being the bottler. Along the way, F&N used the partnership and distribution strength it has built in Malaysia to introduce several drinks of its own brand. Hence, we in Malaysia are introduced with 100Plus, F&N carbonated drinks, Seasons and several other brands - all owned by F&N. Problem is that Coca-cola has the same flavoured drinks. But F&N doing the bottling and distribution so well and Coke, the marketing master was still growing at a nice pace that both were happy with this arrangement for a while. Until both Coca-cola and Pepsi realized that they cannot just rely on carbonated drinks for growth as they are not growing as much anymore as before.

Hence the multi-drink strategy. To have a multi-drink strategy, you will need a multi-marketing strategy and to be able to test out the market for acceptance of any new drinks that they introduce. F&N with its own brands are just not going to do that. Imagine they are bottling for Fanta, Minute Maid while F&N is also selling its own brand of similar range. Surely, Coca-cola being the tai koh (big brother) is not going to allow that as well. Malaysians who do not know, Coca-cola actually has over 100 types of drinks, just that they are not here - yet.

All good things came to an end in 1 September 2011. In fact, the termination was announced much earlier - sometime in 2009 but it took Coca-cola more than 2 years to build its plant in Nilai and together it has to build a distribution channel as well. Remember, Coca-cola did not need to worry about that when F&N was doing the hard work for them.

Good marketing however, is much tougher than good distribution. Coca-cola, is not what it is today (and made Warren Buffett very rich) if not for it being the best marketing company in the world. Apple took over that realm for last 10 years I should say.

Just look at all the strategic shelf space it took over the last year. It has the might. And some time around last year, Fanta (owned by Coca-cola) was brought back. I foresee Coca-cola is not going to stop there having built a 30 acre plant. It will be fighting for market share in the sports drink market and everything else it can make from selling water.

From that, the Malaysian soft drink market is to have 3 major players - Coca-cola, PepsiCo and over time I foresee F&N will drop to be that 3rd player.

So what is the effect to F&N? Tremendous if you look at the contributions the soft drink business brought to them.

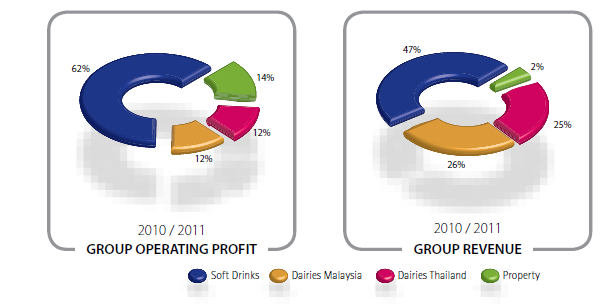
Blue Color shows the contribution from soft drink to F&N in FY2011 (30 Sep)
From the chart above, can see the 62% contribution the soft drink business brought to F&N's Operating Profit from just 47% of revenue - hence it is a very profitable one. For an immediate picture of the effect - below, just look at 1 quarter of results (latest) without Coca-cola.


Operating Profit from soft drinks dropped more than one fold (RM88.36 million to RM41.17 million) . Note that the drop in dairy business in Thailand may be short term though due to massive flood last October - November around Bangkok.

I believe this one quarter impact is not a short term thing. It is going to be a long fight for F&N - one that may turn out to be a big headache for F&N.

Hence, at the current price of RM18.18 valuing F&N Malaysia at more than RM6.56 billion and over 20x FY2011's profit - I think is going to be tough for F&N to maintain in near future. No major property project or any immediate diversification is going to change the immediate loss from Coke's business so soon.

Note: The theme for F&N's Annual Report last year was "Sustainability through Diversity" - hence, you can already guess what they are thinking!

Happy Investing! 

visit www.fb.com/MalaysianInvest